Financial technology, or fintech, has changed how financial services are delivered. Customers can open accounts remotely, make digital payments, access investment platforms, and use technology-enabled financial products without relying on traditional branch-based services.
But what is fintech from a regulatory perspective? It is more than technology applied to finance. It also involves new customer journeys, transaction models, delivery channels, and risk exposures that financial institutions and regulators must understand.
For fintech firms operating in the UAE, this makes anti-money laundering (AML), know your customer (KYC), and customer due diligence (CDD) central to the compliance framework. The Central Bank of the UAE (CBUAE) identifies CDD, KYC, and record keeping as foundational elements of financial crime compliance for institutions within its supervisory scope (Central Bank of the UAE [CBUAE], 2025).
What Is Fintech?
Fintech refers to the use of technology to deliver or support financial products and services. It covers a wide range of activities, including digital payments, online banking, digital lending, investment technology, embedded finance, and certain digital-asset services.
Technology can improve access and operational efficiency, but it can also change the way risks arise.
How Fintech Has Changed Financial Services
Traditional financial services often depended on physical branches and face-to-face interactions. Fintech has moved many of these processes into digital environments.
A customer may now be onboarded remotely, make transactions through an application, or access an investment service without visiting an office.
This creates new considerations for compliance teams. Customer relationships may be established remotely, transactions may move across jurisdictions, and large volumes of customer information may be processed through automated systems.
Why Fintech Creates Distinct Compliance Considerations
Fintech businesses may face risks associated with remote onboarding, cross-border activity, complex ownership structures, digital assets, and automated decision-making.
The issue is not whether technology itself is risky. Rather, the business model, technology, customers, products, and delivery channels need to be considered together.
The CBUAE’s current risk-based guidance specifically calls for institutions to consider factors such as customers, products and services, delivery channels, geographic locations, markets, and operating structures when assessing financial crime risk (CBUAE, 2025).
Why AML and KYC Matter to Fintech Businesses
AML is the broader framework used to prevent and detect money laundering and related financial crime. KYC focuses on identifying and verifying customers and understanding relevant information about them. CDD is broader still, helping firms assess and manage customer risk throughout the relationship.
These terms should not be treated as interchangeable.
A firm may have an effective digital identity system but still have weaknesses in customer-risk assessment, beneficial ownership analysis, transaction monitoring, or ongoing review.
The Relationship Between AML, KYC and CDD
KYC provides important information about the customer. CDD uses that information, together with other relevant factors, to understand risk. AML controls then form part of the broader framework for managing financial crime exposure.
This relationship matters because customer risk does not necessarily remain static.
Why Digital Onboarding Requires Strong Controls
Remote onboarding can increase reliance on digital identity verification, customer information, screening, and automated risk assessment.
Automation can support scale and consistency, but it does not remove the need for governance and oversight. Controls still need to be appropriately designed, configured, tested, and reviewed.
What Is KYC in Fintech?
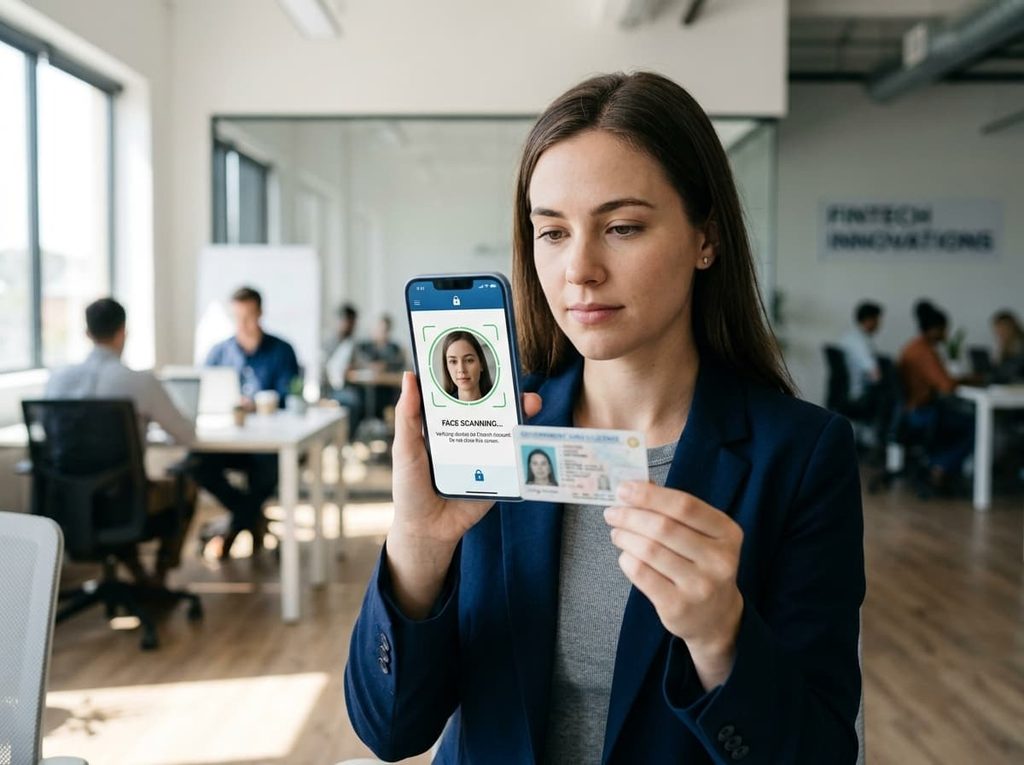
KYC in fintech refers to the processes used to identify and verify customers and obtain information relevant to customer risk.
Customer Identification and Verification
A fintech firm should establish that a customer is who they claim to be using appropriate and reliable information.
For CBUAE-supervised institutions, current guidance requires customer and beneficial-owner identification and verification using reliable and independent sources. The guidance also allows both documentary and non-documentary methods, reflecting a technology-neutral approach (CBUAE, 2025).
The objective, however, is not simply to collect identification documents. Information gathered during onboarding should support the firm’s wider risk assessment.
Identifying Beneficial Owners
Corporate customers can present more complex challenges.
A legal entity may have several ownership layers or control arrangements. Understanding who ultimately owns or controls the customer can therefore be important to the firm’s customer-risk assessment.
Understanding the Customer’s Risk Profile
Relevant factors may include the customer’s business activity, geography, ownership structure, products used, expected transaction activity, and delivery channel.
This allows the firm to apply controls that are proportionate to the risk presented.
What Is CDD and How Does It Apply to Fintech?
Customer due diligence extends beyond basic identity verification.
It helps a firm understand the customer, assess relevant risks, and maintain an appropriate view of the relationship.
Customer Due Diligence Beyond Identity Verification
A customer successfully completing an identity check does not automatically mean the relationship is low risk.
Depending on the business and applicable requirements, CDD may involve understanding the customer’s business, expected activity, ownership, source of funds, or source of wealth.
Enhanced Due Diligence for Higher-Risk Customers
Higher-risk relationships may require additional measures.
These can include situations involving complex ownership, higher-risk jurisdictions, politically exposed persons, unusual activity, or higher-risk products.
A risk-based approach is important. FATF emphasizes that AML/CFT measures should be proportionate to the risks identified rather than applied uniformly to every customer (Financial Action Task Force [FATF], 2025).
Ongoing Customer Due Diligence
CDD should not end when an account is opened.
Customer circumstances can change. Ownership, business activities, geographic exposure, and transaction patterns may all develop over time.
Appropriate ongoing controls can include periodic reviews, trigger-based reviews, customer-information updates, screening, and transaction monitoring.
What Is Fintech? Examining AML, KYC and CDD Requirements for UAE Fintech Firms
The UAE fintech market includes businesses operating across different financial activities and regulatory environments. Therefore, there is no single compliance model that applies identically to every fintech firm.
The first question should be: what activity is the business conducting, and which regulatory framework applies?
Understanding the UAE Regulatory Landscape
Depending on the nature and location of the business, relevant regulatory authorities may include the Central Bank of the UAE (CBUAE), Dubai Financial Services Authority (DFSA), and Financial Services Regulatory Authority (FSRA).
The applicable framework should be established before a firm determines its compliance structure.
For CBUAE-supervised institutions, current guidance covers areas including banks, finance companies, payment service providers, virtual asset service providers, payment token service providers, and other covered financial institutions.
AML Requirements for UAE Fintech Firms
Depending on the applicable framework, an AML programme may need to address:
- Customer risk assessment
- KYC and CDD
- Enhanced due diligence
- Beneficial ownership
- Sanctions screening
- Transaction monitoring
- Suspicious transaction reporting
- Record keeping
- Governance
- Compliance testing
The precise requirements should always be assessed against the firm’s activities and the regulatory framework that applies to it.
Regulatory Expectations Vary by Business Model
A payment business may have different risk considerations from an investment firm or crypto-asset business.
A fintech firm’s compliance framework should therefore reflect its products, customers, transaction flows, geographic exposure, technology, and regulatory status.
Common AML and KYC Weaknesses in Fintech Businesses
Technology does not automatically produce effective compliance.
Treating KYC as an Onboarding Exercise
One common weakness is treating KYC as a document-collection process that ends after account opening.
KYC information should instead support ongoing customer-risk management.
Inadequate Beneficial Ownership Analysis
Complex ownership structures can make it difficult to determine who ultimately owns or controls an entity.
A compliance framework should provide a clear process for identifying and assessing beneficial ownership.
Weak Ongoing Monitoring
Customer behavior can change after onboarding. Monitoring should therefore be connected to the firm’s risk methodology and customer profile.
Over-Reliance on Automated Compliance Technology
Automated systems can support screening and monitoring, but they can also produce false positives, missed alerts, or inappropriate risk classifications if poorly configured.
Technology requires appropriate governance, testing, and human oversight.
Insufficient Governance and Accountability
AML and KYC responsibilities should be clearly assigned. Senior management should have appropriate visibility over material risks, control weaknesses, and remediation.
Building an Effective Fintech AML and KYC Framework
A strong framework should reflect the firm’s actual risk rather than reproduce a generic compliance template.
Establish a Risk-Based Compliance Framework
Consider the firm’s:
- Customers
- Products and services
- Geographic exposure
- Delivery channels
- Transaction patterns
- Operating structure
Controls should be proportionate to the risks identified.
Integrate KYC Across the Customer Lifecycle
A practical framework should connect:
Onboarding → Risk Assessment → Screening → Monitoring → Review
This helps ensure customer information remains relevant throughout the relationship.
Align Technology With Compliance Requirements
Technology should support the compliance framework rather than define it.
Firms should assess whether their systems adequately support identity verification, screening, risk classification, transaction monitoring, case management, reporting, and record keeping.
What Is Fintech? Strengthening AML and KYC Controls Across a Fintech Business
For some firms, strengthening AML and KYC controls may involve targeted remediation. For others, a broader independent review may be appropriate.
An assessment can be particularly useful when entering a new market, launching a new product, introducing new technology, or addressing identified control weaknesses.
What a Comprehensive AML/KYC Review Should Examine
A review may assess:
- Governance and accountability
- AML policies and procedures
- KYC and CDD processes
- Beneficial ownership controls
- Customer-risk methodology
- Screening
- Transaction monitoring
- Enhanced due diligence
- Record keeping
- Compliance testing
The objective should be to identify material weaknesses, assess control effectiveness, and establish appropriate remediation priorities.
Strengthening Controls Without Losing Sight of Business Risk
Effective compliance is not simply a matter of adding more controls.
Controls should be proportionate, risk-based, and aligned with the firm’s regulatory obligations and operating model.
For senior compliance professionals, the more useful question is not whether an AML/KYC framework exists on paper. It is whether that framework remains effective against the risks created by the firm’s current business.
Strengthen Your Fintech Compliance Framework
Fintech changes how financial services are delivered, but it does not remove the need for sound AML, KYC, and CDD controls.
For UAE fintech firms, the appropriate framework depends on the firm’s activities, customers, products, technology, geographic exposure, and applicable regulatory requirements.
Mukhtara provides regulatory compliance and risk advisory support to financial institutions, fintech businesses, investment firms, and other regulated organizations across the UAE and GCC.
If your organization is reviewing its AML/KYC framework, entering a new market, introducing a new financial product, or addressing identified control gaps, explore Mukhtara’s regulatory compliance and risk advisory services or contact the team to discuss your requirements.